Cost of producing the product
Loan interest and repayments
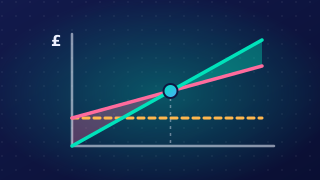
When a business borrows money, the charge for using that money is loan interest. Interest is a fixed cost because it is paid for the period of the loan whether output is high or low. If a business borrows £8,000 at 6% per year, the interest is £480 for the year, so £480 goes into fixed costs for that year, or £40 a month if spread evenly.
A loan repayment is not treated as a fixed cost. Each repayment is made up of part of the borrowed amount plus interest. Only the interest part belongs in fixed costs; the rest reduces what the business owes. If the monthly repayment on that £8,000 loan is £700, only the £40 of interest is a fixed cost, and the other £660 pays off part of the loan.
The loan itself is a separate liability, meaning money the business owes. It is not part of the fixed cost calculation at all. Adding the whole repayment would mix up paying back a debt with the ongoing cost of borrowing, which is why only the interest counts as a fixed cost.
Practise this
Cambridge National Enterprise & Marketing · 3.1 Cost of producing the product