Profit/loss
Profit and loss per unit
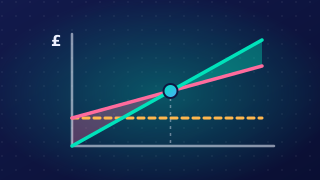
Profit per unit is the amount a business makes or loses on one item sold. You calculate it as selling price per unit − total cost per unit. Total cost per unit is the total costs for the period divided by the number of units made or sold in that period.
Profit or loss on one unit
Subtract total cost per unit from selling price per unit. Do not subtract total costs from total revenue; that finds total profit or loss, not the figure for one unit.
If the selling price per unit is higher than the total cost per unit, the business makes a profit on each unit. If total cost per unit is higher, the result is negative: a loss per unit. For example, a selling price of £8 and total cost per unit of £10.50 gives £8 − £10.50 = −£2.50, a loss of £2.50 per unit. The selling price is still £8; it is the profit figure that is negative. If the two figures are equal, profit per unit is zero, so the business makes neither a profit nor a loss on that unit.
Scaling to a whole output
When the same profit or loss per unit applies to every unit, multiply it by the number of units to find the total for the whole output. A profit of £3.20 per unit on 180 units is £3.20 × 180 = £576 total profit.
Only multiply when the per-unit figure is constant. If a bulk discount makes the cost per unit fall as output rises, one per-unit figure does not apply to every unit. In that case, do not multiply it; use the total costs and total revenue for that output instead.
Practise this
Cambridge National Enterprise & Marketing · 3.3 Profit/loss